 listicle
7 Best Boat Insurance Discounts for Florida Owners
Last Updated: October 27, 2026
Quick Summary
The best boat insurance discounts for Florida owners include safety course credits, bundling boat coverage with home or auto, documented storage and lay-up, paid in full, ownership history, original owner, and safety equipment. Bundling and paid-in-full tend to sit at the higher end of savings, while safety-course and ownership credits sit lower.
- A Florida agency puts standard annual premiums at $200 to $500, or roughly 1% to 1.5% of boat value.
- GEICO's Florida page identifies a Multi-Policy Discount for pairing boat coverage with an auto policy.
- Liberty Mutual advertises up to 5% for customers who have owned any boat for two or more years.
- Some credits are mutually exclusive, such as a lay-up credit and a year-round navigation credit.
- Request the full discount schedule in writing and compare final premiums, not advertised starting rates.
Table of Contents
- How Florida Boat Insurance Discounts Actually Work
- The 7 Best Boat Insurance Discounts for Florida Owners
- How to Lower Boat Insurance Costs Without Cutting Coverage
- The Boat Insurance Safety Course Discount: Who Qualifies
- The Boat Insurance Bundling Discount: Home and Auto
- The Boat Insurance Storage Discount: Indoor, Seasonal, and Lay-Up
- Stacking Discounts: What Insurers Allow and What They Don't
- Comparing Quotes on a Premium Center Console
- Frequently Asked Questions
How Florida Boat Insurance Discounts Actually Work
Boat insurance discounts are price reductions insurers apply to a quoted premium when an owner, vessel, or policy meets specific eligibility rules. For Florida owners, those rules matter more than the headline rate, because advertised starting prices rarely reflect what a premium center console actually costs to insure. A Florida agency puts standard annual premiums at $200 to $500, or roughly 1% to 1.5% of boat value, while a risk advisory firm gives a planning range of 1.5% to 3.5% of value and explicitly labels it illustrative rather than a quote (Atesa Risk Advisors on Florida boat insurance costs).
Below, we break down the seven boat insurance discounts worth pursuing, who qualifies, and how stacking rules limit what you can combine. Owners new to coverage can start with this Florida yacht insurance guide for new owners.
Why Advertised Prices and Discount Headlines Mislead
A discount is a percentage off a number you have not seen yet. Before trusting a discount headline, readers can review yacht insurance policy coverage options to see what a policy actually covers. Insurers advertise savings without publishing the base premium, so a 5% reduction on one carrier's rate can still land above another carrier's undiscounted quote.
The published ranges prove the point. Southern Guard estimates $300 to $600 annually for boats under 26 feet, Progressive advertises liability-only Florida policies from $100 per year, and CNBC Select repeats that $100 figure in its 2026 comparison (CNBC Select's best boat insurance companies comparison). None of those numbers describe a premium offshore center console.
The 7 Best Boat Insurance Discounts for Florida Owners
| Discount | Typical Eligibility | Effort to Qualify | Best For |
|---|---|---|---|
| Safety course | Certificate from approved course | Low | New and returning boaters |
| Bundling | Home or auto policy with same insurer | Medium | Owners with existing policies |
| Storage / lay-up | Documented indoor or seasonal storage | Medium | Seasonal and stored vessels |
| Paid in full | Pay annual premium upfront | Low | Cash-flow-flexible owners |
| Ownership history | Prior boat ownership record | Low | Experienced owners |
| Original owner | First-title purchase | Low | New-boat buyers |
| Safety equipment | Installed alarms, trackers, extinguishers | Low | All owners |
Safety Course Discount
The boat insurance safety course discount rewards documented education. GEICO lists a boat-safety-course discount among its Florida offerings, and Insurify's comparison guide names boating education courses as a common savings path (GEICO Florida boat insurance page).
Bundling Discount
The boat insurance bundling discount is the largest single lever for most owners. GEICO's Florida page explicitly identifies a Multi-Policy Discount for pairing boat coverage with an auto policy, and Progressive advertises multi-policy savings as well (Progressive boat insurance). The eligibility rule is straightforward: the boat policy must sit with the same carrier as the home or auto policy, and the companion policy must remain active.
Storage and Lay-Up Discount
The boat insurance storage discount reflects reduced risk. Indoor rack storage, covered lifts, and documented lay-up periods all lower exposure, and GreatFlorida names lay-up periods alongside safety courses and bundling as meaningful premium reducers (GreatFlorida's 2026 boat insurance guide). The eligibility rule depends on documentation, not intention: insurers want to see where the vessel sits, whether the storage is enclosed, and the exact dates of any lay-up period.
Paid-in-Full and Ownership Discounts
CNBC Select notes Progressive's paid-in-full, safety-course, and original-owner credits in its 2026 comparison. Liberty Mutual advertises up to 5% for customers who have owned any boat for two or more years, subject to eligibility.
Safety Equipment Discount
Installed alarms, tracking devices, fire extinguishers, and other safety equipment can earn a credit with carriers that recognize the reduced theft and damage exposure. Eligibility requires proof of installation, a receipt, an installation record, or a photo of the equipment in place. This is the discount most often left on the table because owners install the gear and never tell the insurer.
How Much These Discounts Actually Save
No carrier publishes a universal savings figure, and any article quoting one number for every owner is guessing. Individual credits typically range from a few percent to low double digits, with bundling and paid-in-full at the higher end and safety-course and ownership credits at the lower end. The only reliable number is the one on your quote, which is why stacking matters as much as the credits themselves.
How to Lower Boat Insurance Costs Without Cutting Coverage
Our method, refined over years of quoting premium center consoles: request the discount schedule in writing, then compare three carriers at identical coverage limits. Our breakdown of center console boat depreciation rates explains why a well-documented vessel history supports both a better resale and a cleaner insurance conversation.
Reach out now to see how we can help with your boating needs! →
The Boat Insurance Safety Course Discount: Who Qualifies
Most major carriers extend the boat insurance safety course discount to any named operator who completes an approved course, not just the policyholder. That detail matters on a family boat with multiple drivers. Eligibility usually requires a certificate of completion, and some insurers specify course providers or minimum instruction hours. Ask your agent which certificates your carrier accepts before you pay for a course, and keep the certificate on file with your policy documents. Proactive education extends beyond formal certification, as incorporating consistent boating safety tips into your family outings ensures that every passenger remains secure while on the water.
The Boat Insurance Bundling Discount: Home and Auto
GEICO's Multi-Policy Discount requires a GEICO auto policy; Progressive advertises similar multi-policy savings.
The Boat Insurance Storage Discount: Indoor, Seasonal, and Lay-Up
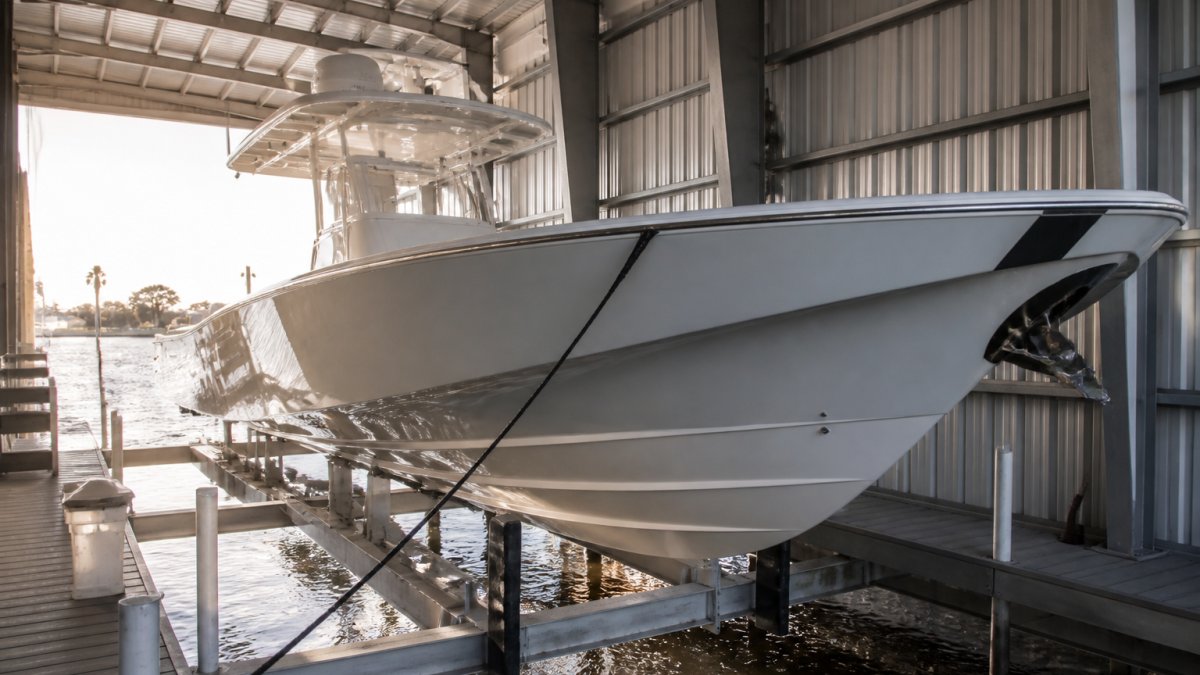
The boat insurance storage discount depends on documentation, not intention. Insurers want to see where the vessel sits, whether the storage is enclosed, and the exact dates of any lay-up period. Seasonal storage in a hurricane-exposed region carries more weight than the same arrangement inland, because storm damage is the exposure the carrier is pricing. Confirm how the policy defines lay-up dates and what happens if you launch early, a mid-season splash can void the credit.
Stacking Discounts: What Insurers Allow and What They Don't
A second mechanism is mutual exclusivity. Some pairs of credits are alternatives rather than additions: a lay-up credit and a year-round navigation credit, for example, may not both apply because they describe different risk profiles. The carrier's rate manual decides which pairs are exclusive, and the agent can usually see the rule in the quoting system.
Advertised Savings vs. Applied Savings
This is why the quote comparison method below matters more than any discount list. The goal is not to collect the most credits; it is to confirm which credits actually reduced the premium on the quote in front of you. To judge whether a quoted premium is reasonable, see this premium center console cost guide.
Florida-Specific Eligibility and Regional Differences
Hurricane exposure is the factor owners most often underestimate. Carriers price storm risk into the base premium, and a storage or lay-up credit is one of the few levers that directly addresses that exposure. An owner who claims a lay-up credit but keeps the vessel in the water through hurricane season is creating a claims dispute, not a savings strategy.
A Repeatable Quote-Comparison Method
- Request the full discount schedule in writing from each carrier
- Confirm coverage limits, deductible, and navigation area are identical across quotes
- Ask which discounts are mutually exclusive
- Ask for the combined discount cap, if any
- Compare final premiums, not advertised starting rates
- Re-shop at every renewal, since eligibility rules change
Practical Steps to Qualify for More Discounts
- Complete an approved boating-safety course and keep the certificate with your policy documents.
- Photograph and inventory installed safety equipment, alarms, trackers, extinguishers, and send the record to your agent.
- Obtain written proof of storage type and location, including whether the facility is enclosed.
- Document lay-up dates in writing and confirm how the policy defines them.
- Keep a record of prior boat ownership to support ownership-history credits.
- Confirm the companion home or auto policy is active before relying on a bundling credit.
The Trade-Off: Discounts vs. Coverage
The final caution is the one competitors skip. A lower premium achieved by shaving hull value, dropping liability limits, or narrowing the navigation area is not a discount, it is a coverage decision with a claims-time cost. Hull value drives both premium and settlement, so underinsuring to save a few hundred dollars a year can cost you tens of thousands at claim time. The discounts worth pursuing reduce premium without reducing protection: safety course, bundling, paid-in-full, documented storage, and safety equipment. If a quote is cheaper because coverage is thinner, compare coverage before price.
Comparing Quotes on a Premium Center Console
If you are acquiring a premium center console, Primo Yachts provides specialist brokerage guidance. Get started with Primo Yachts.
Frequently Asked Questions
What discounts are available for boat insurance?
The most common boat insurance discounts include a boating safety course discount, a bundling discount for pairing boat coverage with home or auto policies, a storage or lay-up discount, and savings for paying the annual premium in full. Some insurers also reward original owners or boaters with a clean claims history. Each carrier sets its own eligibility rules, so the only way to confirm what you qualify for is to request quotes from several insurers and ask which discounts each one applies.
Does taking a boating safety course reduce boat insurance?
Several insurers advertise a boat insurance safety course discount, and GEICO lists one among its boat savings. The size of the reduction depends on the carrier, the course, and the rest of your policy profile, and no source in this research publishes a fixed percentage. Completing a recognized course is still worth doing: it costs little, it may lower your premium, and it sharpens the handling skills that matter most on a high-performance center console.
Can bundling boat and auto insurance save money?
A boat insurance bundling discount is one of the most widely advertised savings. GEICO offers a multi-policy discount when you pair boat coverage with a GEICO auto policy, and Progressive advertises bundling with auto or homeowners insurance. The catch is that the discount applies only to policies the same insurer writes, so compare the bundled total against separate quotes from other carriers before you commit. A bundle that saves on paper can still cost more overall.
Does storing a boat indoors lower insurance costs?
Storage can affect your premium, and some guidance identifies lay-up periods as a premium-saving option. Indoor or covered storage and a defined seasonal lay-up reduce storm and sun exposure, which insurers price into physical damage coverage. The boat insurance storage discount is not automatic, though. Ask each carrier how it rates your specific marina, lift, or rack arrangement, and confirm whether a lay-up period limits when the vessel can be on the water.
Is boat insurance required in Florida?
Florida does not require insurance for every recreational boat, but coverage becomes mandatory in certain situations, and a lender or marina may require it as a condition of financing or berthing. For a high-value center console, physical damage and liability coverage protect a significant asset regardless of the legal minimum. Review policy limits, deductibles, and navigation area with a licensed agent so the coverage matches how and where you actually run the boat.